China Heavy Truck Exports Set September Record: Africa and Latin America Hit New Highs
Customs-based broker tracking puts September 2026 heavy truck exports at about 47,900 units, up 42.6% year on year - a single-month record. Africa took 46.7% of the total and Latin America surged 129%. Here is what the numbers mean for used truck buyers.
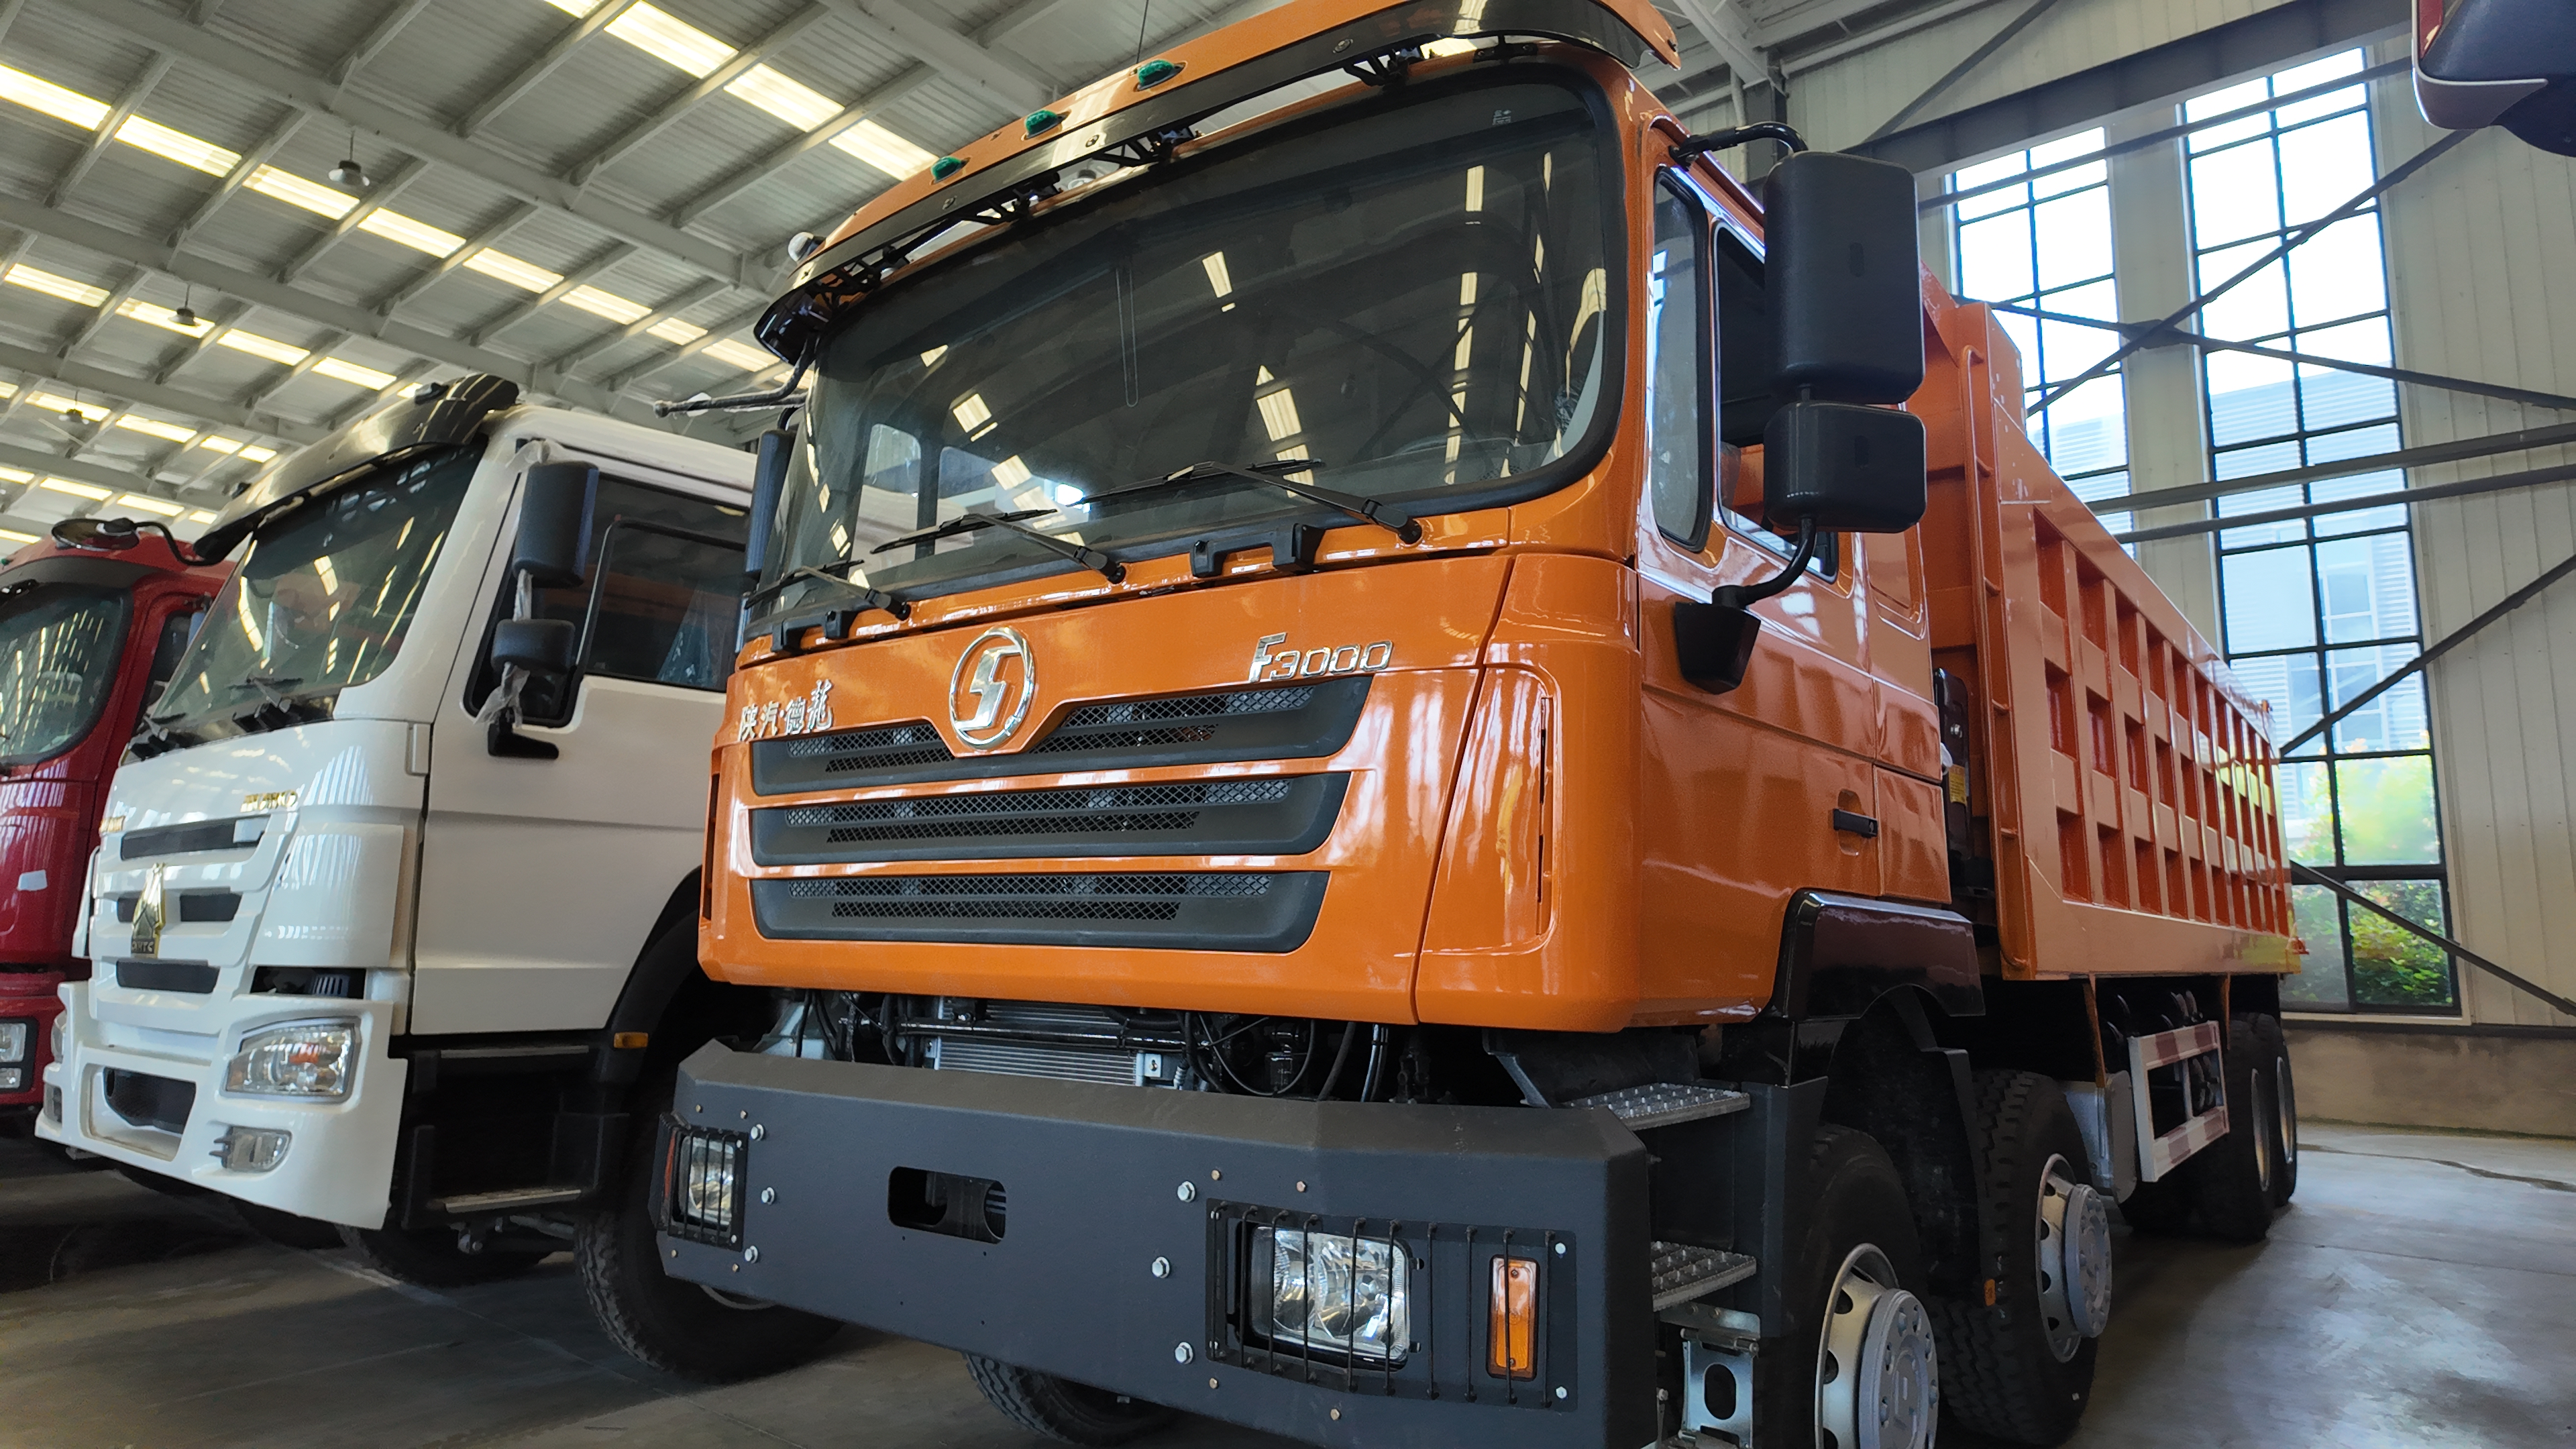
China's heavy truck exports just posted their strongest single month on record. Customs data tracked by the Zhongtai Securities automotive research team put September 2026 exports at about 47,900 units, up 42.6% year on year and 16.6% month on month, with January-September cumulative exports around 363,500 units, up 40.5% (reported). A second broker tracker reading the same customs HS codes reports a slightly lower monthly total of about 45,000 - the trackers' HS-code scopes differ slightly, so treat the totals as directional while the trend is unambiguous. For buyers, this is the demand backdrop behind every quote you receive. We covered the first-half structure in our H1 Africa data report and the big picture in the global trade review; here is the September picture.
Where the trucks went in September
- Africa: about 22,400 units, +49.1% year on year - the highest monthly figure since 2015, taking 46.7% of total exports (reported). Industry tracking of the same customs data puts January-September Africa volume near 148,000 units, up 64% - the structural lead continues.
- Latin America: about 5,400 units, +129.3% year on year - also a post-2015 record, 11.3% of the total. Peru's demand is growing fastest, making Latin America the fastest-rising increment market.
- Southeast Asia: about 9,100 units, +17.8%, 19.0% of exports, with clear month-on-month improvement.
- Central Asia: about 2,700 units, +13.9%. West Asia: about 2,400 units, down 40% - the only region in decline.
- Top five destinations: Vietnam (4,328), Tanzania (3,073), Nigeria (2,573), Peru (1,733) and Kenya (1,678).
The divergence behind the record
Domestic heavy truck wholesale sales fell roughly 10% year on year in September while exports hit a record - the hot-export, soft-domestic split that has defined 2026. The same customs-based reports project full-year exports near 450,000 units versus about 364,000 in 2025 (reported). Meanwhile domestic new-energy penetration reached roughly 49% of September sales, which accelerates the replacement cycle feeding the used EV supply wave we covered in the used EV inflection report. Export strength is also why used prices have held firmer than domestic fleet economics alone would suggest - benchmark any quote against our FOB price baselines.
What September's data means for used truck buyers
- Tanzania, Nigeria and Kenya all sit in the global top five. New-truck volume builds the densest parts and service networks, and used truck buyers in those markets ride the same infrastructure. Route planning: our Tanzania guide, Lagos clearance guide and Kenya guide.
- Latin America is the market to watch. Peru's surge signals a new corridor opening; before committing, verify dealer presence and parts availability - the same due-diligence logic we advise in the Latin America export review.
- Record flows today are tomorrow's used supply. Trucks shipped new in 2025-2026 will start re-entering local markets as used stock, and financing is following the volume, as covered in the financing guide.
- West Asia's decline is a caution flag. Falling volumes can mean softer service investment - factor that into resale assumptions for the region.
The strategic takeaway matches what the analysts themselves conclude: exports are now the growth engine of China's truck industry, and the markets scaling fastest - East Africa, West Africa and the Andes - are exactly where service networks are being built. Buyers who align sourcing with those corridors inherit the infrastructure. For the year's earlier data, revisit the H1 Africa report and the global trade review.